Insurance companies sit on enormous amounts of useful information, but much of it is difficult to access at the moment someone actually needs it.
Underwriters may need to search guidelines, submissions, loss histories, and exposure documents. Claims adjusters work across policies, endorsements, reports, photographs, correspondence, and repair estimates. Service teams answer questions using product rules and policy wording that can vary by state, line of business, customer, and effective date.
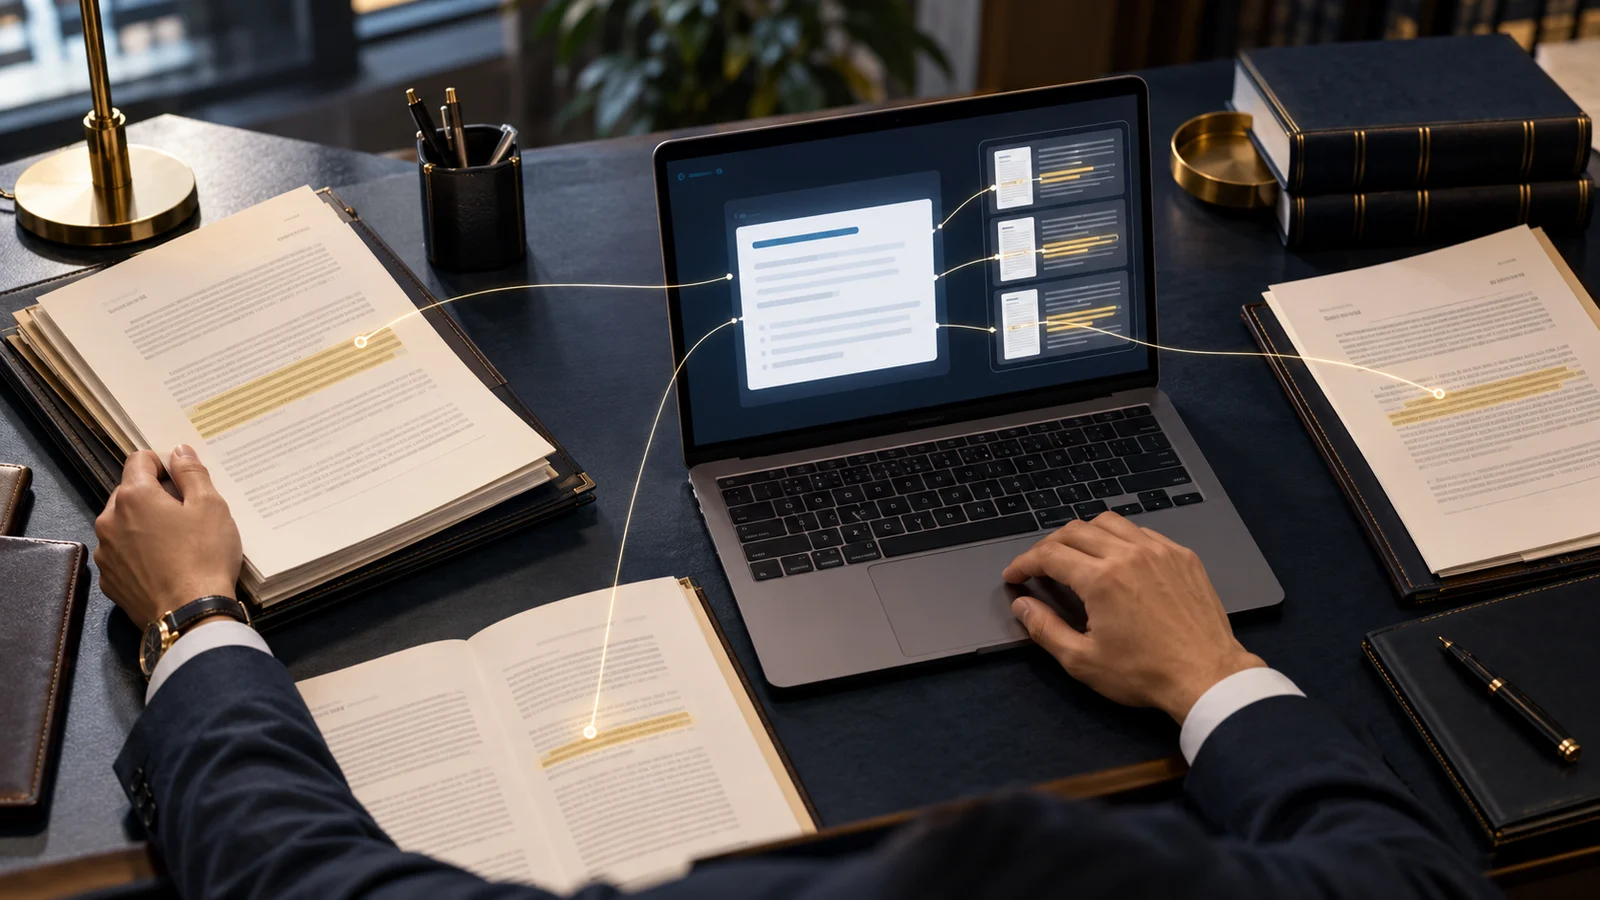
Retrieval-augmented generation can turn those fragmented sources into a conversational knowledge layer. Instead of asking a large language model to answer from its general training, a RAG system first retrieves relevant information from approved insurance data and then uses that evidence to construct a response.
That does not make the answer automatically correct.
An insurance RAG system also needs accurate document retrieval, source citations, version control, permission-aware access, reliable data pipelines, and clear human-review boundaries. These requirements become especially important when AI participates in underwriting, claims, pricing, or other consequential insurance workflows.
The NAIC's current AI guidance reflects that concern. Its Model Bulletin on the Use of Artificial Intelligence Systems by Insurers emphasizes governance and compliance with applicable insurance laws, while regulatory work in 2026 continues to focus on AI-system evaluation, data quality, model oversight, fairness, and third-party technology.
The following companies combine RAG engineering with capabilities that are particularly relevant to insurers.
Insurance RAG Companies at a Glance
| Company | Best Fit | Notable Strength |
|---|---|---|
| EPAM | Large carriers and reinsurers | Enterprise insurance transformation, underwriting, claims, RAG |
| Tredence | Data-intensive insurers | RAG, GenAI, insurance analytics, claims intelligence |
| SoftServe | Document-heavy and multimodal insurance workflows | RAG across text, tables, images, and enterprise data |
| Itransition | Insurance knowledge assistants and custom platforms | Proven insurance GenAI knowledge retrieval |
| LeewayHertz | InsurTech and custom insurance AI | RAG, AI agents, claims, underwriting, policy workflows |
| Addepto | Insurers with fragmented data environments | RAG, insurance analytics, data engineering, governance |
| SoluLab | Carriers, MGAs, and InsurTech startups | Policy, claims, underwriting, and custom RAG applications |
| Kanerika | Enterprises that need strong data foundations | Hybrid retrieval, ingestion pipelines, enterprise RAG |
1. EPAM
Best for: Large insurers and reinsurers building enterprise AI across underwriting and claims
EPAM combines insurance consulting, custom software engineering, data platforms, and generative AI at a scale that suits complex carriers.
Its insurance practice covers underwriting, claims, distribution, policy systems, and wider transformation programs. EPAM also works directly with RAG and agent-based architectures for insurance operations, including systems that combine structured and unstructured data for underwriting, claims, risk analysis, policy servicing, and regulatory workflows.
The company is particularly relevant when the challenge extends beyond answering questions from policy PDFs.
An enterprise insurer may need a RAG application to pull information from submission documents, internal underwriting guidelines, policy-administration systems, claims platforms, customer records, external risk data, and regulatory material.
EPAM's insurance work also includes AI-enabled claims capabilities for document ingestion, policy and coverage validation, fraud checks, calculations, customer communication, and workflow automation.
Why EPAM stands out
EPAM is a good fit for organizations needing:
- underwriting copilots
- claims knowledge systems
- policy-servicing assistants
- RAG over structured and unstructured insurance data
- Guidewire and core-system integrations
- regulatory and risk workflows
- agentic AI connected to enterprise systems
Its scale is an advantage for multi-year transformation programs, although smaller insurers with a tightly scoped RAG pilot may prefer a more specialized development team.
2. Tredence
Best for: Insurers where RAG is closely connected to analytics and enterprise data
Tredence has a strong combination of insurance, data science, analytics, GenAI, and data-engineering capabilities.
Its banking, financial-services, and insurance practice includes enterprise GenAI, governed knowledge bots, data modernization, model management, and AI-powered workflows. The company says it has more than 25 prebuilt GenAI accelerators across banking, financial services, and insurance.
Tredence has also delivered GenAI work for a commercial insurance carrier where the system synthesized information from policy documents, police and fire reports, photographs, repair estimates, damage assessments, weather information, and other evidence into structured claims reports.
Its broader GenAI architecture includes natural-language access across structured and unstructured data and context-driven RAG approaches for financial-services applications.
Why Tredence stands out
Tredence deserves consideration for:
- claims intelligence
- underwriting copilots
- policy interpretation
- regulatory knowledge systems
- insurance analytics
- document-heavy decision support
- enterprise AI governance
It can be particularly valuable when the insurer needs to improve the underlying data architecture at the same time as building the RAG interface.
3. SoftServe
Best for: Insurance workflows involving tables, forms, images, and other multimodal documents
Insurance documents rarely contain clean text alone.
Claims can contain photographs, estimates, tables, forms, scanned reports, correspondence, and policy wording. Underwriting files can include financial statements, schedules, property information, maps, and supporting images.
SoftServe's multimodal RAG system is designed to retrieve information across text, images, and tables within a unified architecture rather than reducing everything to plain text.
The company also has substantial financial-services and insurance experience. Its current financial-services practice covers insurance, intelligent underwriting, claims processing, document analysis, compliance, and AI-driven customer operations.
SoftServe has additionally worked on insurance-specific AI projects, including GenAI systems for insurance proposal design and intelligent document processing for insurance analytics.
Why SoftServe stands out
SoftServe can be particularly useful for:
- claims document analysis
- underwriting document intelligence
- insurance product knowledge assistants
- proposal and quote support
- multimodal policy and claims retrieval
- customer-service copilots
Its multimodal capabilities matter when information contained inside an image or table is just as important as nearby text.
4. Itransition
Best for: Insurance knowledge retrieval and custom GenAI applications
Itransition has a particularly relevant insurance RAG example.
The company developed a GenAI knowledge-retrieval agent for a large insurance provider whose agents struggled to locate information across an extensive knowledge base of policy documentation, guidelines, and related content.
The resulting assistant allows insurance agents to ask questions in natural language, receive concise answers, and follow links back to the original sources. Itransition reports that the deployment reduced policy-information search time and improved agent productivity.
Its broader GenAI engineering practice includes RAG, embeddings, chunking, retrieval optimization, continuous testing, AI agents, and enterprise integrations.
Why Itransition stands out
Itransition is especially relevant when the use case is clear and practical:
"Help our people find the right insurance information faster."
Potential projects include:
- policy knowledge assistants
- insurance-agent copilots
- customer-service knowledge systems
- claims guidance
- internal procedure search
- custom insurance portals with embedded AI
Its broader software-development capability is also useful where RAG needs to be incorporated into an existing platform rather than delivered as a separate chatbot.
5. LeewayHertz
Best for: InsurTech companies and insurers combining RAG with AI agents
LeewayHertz has a dedicated insurance AI practice covering claims, underwriting, policy management, compliance, customer support, and system integration.
Its current insurance services include GenAI development, AI agents, data engineering, underwriting support, claims processing, policy servicing, and workflow integration.
RAG becomes particularly useful in these workflows when an AI agent needs supporting knowledge before taking the next step.
For example, an underwriting copilot could retrieve the applicable underwriting guideline, compare it with submission details, flag a conflict, draft an explanation, and route the case to an underwriter.
LeewayHertz specifically describes retrieval-grounded generation for underwriting tasks such as appetite assessment, eligibility review, guideline interpretation, sanctions checks, and preparation of explanations tied to approved criteria.
Why LeewayHertz stands out
Consider LeewayHertz for:
- underwriting copilots
- insurance AI agents
- policy-management systems
- claims assistants
- compliance knowledge tools
- InsurTech products
- workflow automation connected to RAG
Organizations adopting agentic AI should define strict limits around actions involving coverage, claim settlements, underwriting decisions, customer communications, and other regulated activities.
6. Addepto
Best for: Insurers whose RAG problems begin with fragmented enterprise data
Addepto combines RAG and generative AI with data engineering, analytics, machine learning, and insurance-domain capabilities.
Its finance and insurance practice covers underwriting, claims, fraud, regulatory reporting, model governance, servicing, and customer operations. Addepto specifically describes RAG-generated suggestions and next-best actions for service teams while emphasizing traceability and governance for regulated workflows.
This matters because many insurance RAG projects are actually information-architecture projects disguised as chatbot projects.
A carrier might have policy data in one core system, underwriting rules in SharePoint, claims documents in another repository, customer information in a CRM, and years of archived PDFs stored elsewhere.
An LLM cannot solve those structural problems by itself.
Why Addepto stands out
Addepto is worth considering for:
- data-heavy insurers
- underwriting intelligence
- claims automation
- customer-service RAG
- fraud and risk workflows
- regulatory reporting
- AI data governance
Its broader data capabilities can make it useful where substantial ingestion, transformation, lineage, and governance work is required before RAG can perform reliably.
7. SoluLab
Best for: Carriers, MGAs, and InsurTech startups building custom RAG products
SoluLab provides dedicated RAG development and explicitly identifies insurance as a target industry.
Its insurance RAG use cases include retrieving policy documents, claims information, underwriting guidelines, and compliance-related content from enterprise repositories.
The company also builds AI claims automation for carriers, managing general agents, and InsurTech startups. Its workflow work covers submission intake, ACORD documents, claims information, human review, audit trails, and insurance-specific document processing.
That combination makes SoluLab particularly relevant when the RAG layer needs to become part of a complete operational product.
Why SoluLab stands out
Potential applications include:
- claims assistants
- policy Q&A
- underwriting knowledge tools
- insurance customer portals
- compliance retrieval
- broker assistants
- custom InsurTech SaaS
SoluLab is more than a retrieval specialist, which can be useful for companies that also need frontend development, APIs, workflow automation, cloud deployment, and product engineering.
8. Kanerika
Best for: Insurers that need strong ingestion pipelines and hybrid enterprise retrieval
Kanerika focuses on enterprise RAG architecture, data pipelines, GenAI, analytics, and data engineering.
Its RAG services include hybrid search across structured and unstructured information, document preparation, embedding architecture, enterprise-data connectors, continuous content updates, and retrieval design around actual user queries.
Kanerika's broader GenAI practice also includes secure LLM integration and RAG implementation for enterprise knowledge bases.
Those capabilities can be valuable in insurance because the most useful answers frequently require information from several types of sources.
A policy-service question might require retrieving wording from a document while also checking structured customer or policy information. A pure vector-search architecture may not be the best way to handle both.
Why Kanerika stands out
Kanerika can fit insurers needing:
- enterprise knowledge RAG
- hybrid structured/unstructured retrieval
- continuous document ingestion
- data-platform modernization
- secure LLM integration
- analytics connected to GenAI
It is especially relevant where getting insurance information into a clean, continuously updated retrieval layer is the project's main technical difficulty.
What Makes Insurance RAG Different?
Insurance is unusually dependent on documents.
Policies, endorsements, underwriting manuals, submissions, claims reports, adjuster notes, forms, contracts, regulations, actuarial material, and correspondence all contain information that can change the result of a workflow.
RAG helps surface this information, but several insurance-specific problems require additional engineering.
Policy wording must be matched to the correct contract
An insurer may have many versions of seemingly similar policies.
The correct answer could depend on:
- policy form
- endorsement
- state
- product
- effective date
- coverage period
- customer
- renewal version
A RAG system that retrieves the most semantically similar clause from the wrong policy can produce a convincing but incorrect answer.
Retrieval therefore needs metadata filtering and policy-level context, not simply vector similarity.
Underwriting often requires several evidence sources
An underwriter may need to consider submission forms, loss runs, property information, internal appetite guidelines, prior claims, financial information, external risk signals, and underwriting authority rules.
The RAG architecture may therefore need to combine document retrieval with structured database access and external APIs.
This is one reason context-driven and hybrid retrieval can be more appropriate than a single vector index.
Claims are inherently multimodal
A property claim could contain:
- photographs
- repair estimates
- police reports
- adjuster notes
- policy wording
- invoices
- weather information
- correspondence
- scanned forms
A system that extracts only text may miss critical evidence.
Multimodal retrieval and document intelligence can therefore be particularly valuable for claims applications.
Historical versions still matter
An old insurance document should not necessarily be deleted.
A claims adjuster reviewing a loss from several years ago may need the policy wording and procedures that were effective at that time rather than the versions currently in force.
That creates a more complex requirement than simple "always retrieve the newest document."
The system needs temporal context.
Access control should be part of retrieval
Customer information and claims documents can contain sensitive personal and financial data.
Authorization should determine which information can be retrieved before it is included in the model's context.
Filtering the generated answer afterward is a weaker control because sensitive information may already have been exposed to the model or logging infrastructure.
Practical RAG Use Cases in Insurance
RAG works best where employees repeatedly need to locate, understand, and combine information from trusted insurance sources.
Underwriting copilots
A RAG assistant can retrieve underwriting guidelines and compare them with submission information.
The output could identify relevant requirements, highlight missing information, and link directly to the applicable guideline.
The underwriter remains responsible for the consequential decision.
Claims assistance
Adjusters can retrieve policy language, endorsements, procedural guidance, claim documents, and similar internal knowledge from one interface.
RAG can also support the creation of draft claim summaries grounded in available evidence.
Policy servicing
Customer-service representatives often answer detailed questions about coverage, exclusions, renewals, endorsements, billing, and policy procedures.
RAG can make approved policy and product knowledge easier to access while returning the supporting source.
Broker and agent support
An internal assistant can help distribution teams locate product information, eligibility requirements, appetite guidelines, forms, or sales materials without searching multiple systems.
Compliance and regulatory knowledge
Insurance regulations differ across jurisdictions and evolve over time.
A RAG system can make regulatory information easier to search while connecting answers to source documents for verification.
Claims and underwriting training
Experienced insurance professionals accumulate institutional knowledge that can be difficult to transfer.
RAG can give newer employees guided access to approved procedures, manuals, examples, and reference material without requiring them to know exactly where each document is stored.
How to Evaluate an Insurance RAG Development Company
A vendor should be able to demonstrate more than a chatbot answering simple policy questions.
The evaluation should test how the system handles real insurance complexity.
Ask how retrieval quality is measured
Good teams should evaluate retrieval separately from answer generation.
If the wrong answer appears, you need to know whether:
- the correct document was never retrieved,
- the correct document ranked too low,
- the right passage was retrieved but misinterpreted,
- or the model generated unsupported information.
Those failures require different fixes.
Test policy versions and endorsements
Create questions where two documents contain similar language but only one applies.
Ask the vendor to show how metadata, effective dates, product information, and policy identifiers affect retrieval.
Test questions with no valid answer
A RAG system should not feel compelled to respond.
If the approved knowledge base contains insufficient evidence, the safest result may be:
Insufficient information. Human review required.
Abstention behavior is especially important in underwriting and claims workflows.
Ask how source citations work
Users should be able to inspect the evidence supporting important outputs.
A citation should ideally lead to the relevant passage rather than merely naming a 200-page policy document.
Review integrations carefully
Insurance RAG may need to interact with:
- policy administration systems
- claims platforms
- CRM
- Guidewire
- Duck Creek
- document repositories
- data warehouses
- underwriting workbenches
- broker portals
- regulatory databases
Ask whether the information will be copied into an index, accessed through APIs, queried directly, or retrieved through another method.
Evaluate governance before production
Insurance AI is receiving growing regulatory attention.
The NAIC states that insurers remain responsible for ensuring decisions or actions supported by AI comply with applicable insurance laws, and its regulatory work includes AI governance, risk mitigation, potentially high-risk models, data inputs, and third-party systems.
A useful vendor evaluation should therefore cover:
- audit logs
- model and prompt changes
- access controls
- data provenance
- testing
- human oversight
- model monitoring
- third-party dependencies
- incident handling
- bias and fairness controls
NIST's Generative AI Profile can also serve as a voluntary reference for identifying and managing risks across the GenAI lifecycle.
Which Insurance RAG Company Is the Best Fit?
There is no universal winner because insurers have very different technology environments and business priorities.
EPAM is particularly suitable for major carriers and reinsurers undertaking large transformation programs across underwriting, claims, data, and core systems.
Tredence is a strong candidate when insurance RAG is closely tied to analytics, enterprise data, claims intelligence, or governed GenAI.
SoftServe deserves consideration for document-heavy and multimodal workflows where photographs, tables, forms, and text need to be processed together.
Itransition stands out for practical insurance knowledge-retrieval systems and custom software integration.
LeewayHertz fits organizations that want to combine RAG with AI agents across underwriting, claims, policy servicing, and operational workflows.
Addepto is particularly relevant when the insurer first needs to organize fragmented data and build a stronger AI-ready information layer.
SoluLab can suit carriers, MGAs, and InsurTech companies that need the complete application built around the retrieval system.
Kanerika fits organizations where enterprise ingestion pipelines and hybrid retrieval are the central technical requirements.
The final decision should be based on performance against your own insurance documents and workflows.
Give shortlisted vendors overlapping policy versions, messy claims files, long underwriting guides, restricted customer information, questions with missing evidence, and examples requiring data from more than one system. That test will tell you considerably more than a polished chatbot demonstration.